Car Research for El Cajon, CA
No results found
Showing 11 - 12 of 12 Cars Research in El Cajon, CA
A complete, consumer-friendly breakdown of the differences between buying and leasing a vehicle, including ownership, costs, long-term value, and guidance tailored for shoppers at El Cajon Mitsubishi.
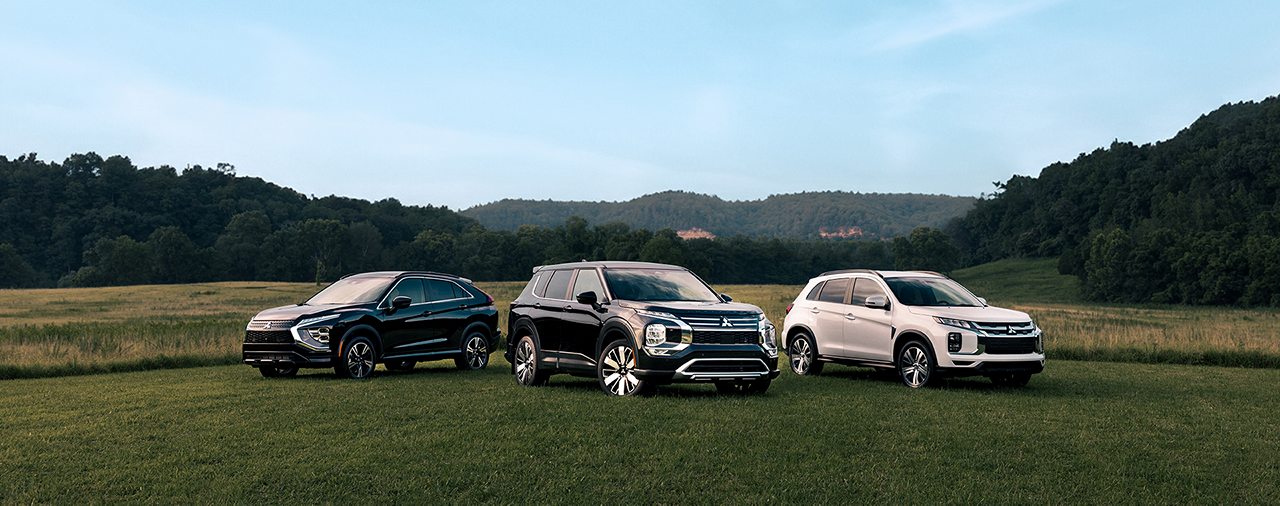
Explore the 2025 Mitsubishi Outlander, Outlander Sport, and Eclipse Cross — feature-packed SUVs priced under $30,000. El Cajon Mitsubishi proudly serves drivers across El Cajon, San Diego, La Mesa, Santee, and Lakeside with unbeatable value and advanced Mitsubishi engineering.
Payment options include cash, checks, debit, credit cards, and financing through partner lenders. Online payment portals are available for service or parts.
Some lenders offer first-time buyer programs created for customers with limited credit histories. These programs may feature flexible approval criteria and competitive rates. Finance specialists can explain eligibility requirements and help you choose the best option.
Zero-percent financing promotions are occasionally available on select Mitsubishi models, depending on manufacturer incentives and your credit qualifications. These offers are limited-time and subject to approval. Your dealership’s finance team can help check current promotional availability.
A co-signer with strong credit can improve your chances of approval or help you secure better loan terms. Lenders cannot require a co-signer unless you apply jointly. Both parties share full responsibility for the loan, so it's important to understand the obligations before proceeding.
Pre-approval lets you know what loan amount and interest rate you qualify for before visiting the dealership. It helps set your budget and makes comparing offers easier. Multiple credit inquiries within a short time window are typically treated as a single inquiry.
Leasing typically provides lower monthly payments and allows frequent upgrades, but mileage limits apply and you do not own the vehicle. Buying builds equity and comes without mileage restrictions, though payments are generally higher. The best choice depends on your driving habits, budget, and long-term plans.
Most experts recommend a down payment between 10% and 20%, depending on whether the vehicle is new or used. Larger down payments reduce the loan amount and monthly payment. Trade-in value can also contribute to your down payment. Your finance team can help compare different scenarios.
APR represents the yearly cost of borrowing, including interest and lender fees. It helps consumers compare loan offers on equal terms. Your APR depends on factors such as credit score, loan term, vehicle age, and market rates. A lower APR means paying less interest over the life of the loan.